January arrives and you realize you have not touched your books since last winter. A full year of transactions sits uncategorized. Receipts are stuffed in a shoebox. Bank statements remain unopened. The tax deadline looms and panic sets in. The solution is not to abandon the year and hope for the best. It is a structured catch up process that rebuilds your books month by month so you can file an accurate return and claim every deduction you earned.
Why Waiting Until Tax Season Backfires
Bookkeeping is a monthly discipline. When you defer it for twelve months, you create a backlog that no single weekend can resolve. You forget what individual transactions were for. You lose receipts that proved legitimate deductions. You miss the small errors that, left unchecked, compound into a distorted financial picture.
The tax deadline is unforgiving. Filing late triggers failure to file penalties that grow every month your return sits unsubmitted. Filing with inaccurate numbers triggers a different problem entirely. The IRS matching system compares your return against the 1099s and W2s it received from your clients and platforms. A mismatch generates an automated notice that demands an explanation.
The deeper cost is strategic. When you do a full year of bookkeeping in a panic, you have no opportunity to plan. You simply report what happened. You cannot adjust your spending, time your purchases, or structure your entity to reduce your tax burden. You forfeit the proactive strategies that separate a business that survives tax season from one that thrives through it.
The Real Cost of a Year of Neglect
A year of neglected books creates three distinct categories of damage. Each one compounds the others. Understanding the cost helps you commit to the cleanup process instead of giving up halfway through.
The first cost is lost deductions. Every receipt you cannot find is a deduction you cannot claim. Every transaction you categorize as generic office expense instead of its true category is a missed opportunity to reduce your taxable income. Over a full year, those missed deductions add up to real money left on the table.
The second cost is inaccuracy. When you categorize twelve months of transactions in a rush, you make mistakes. You duplicate entries. You assign personal expenses to business accounts. You record revenue in the wrong period. Those errors distort your profit and loss statement and produce a tax return that does not reflect reality.
The third cost is stress. The mental weight of an unfinished tax return drains your focus from the business you are trying to run. You lose sleep. You snap at your team. You make poor decisions because your attention is consumed by a problem you could have prevented with a monthly habit.
The Signals You Waited Too Long
- You have no categorized transactions for the entire year
- Your receipts live in a shoebox or a glove compartment
- You cannot produce a current profit and loss statement
- You do not know your true net profit for the year
- Your bank balance is your only measure of financial health
- You have not reconciled a single account in twelve months
- You dread opening your accounting software
Step One: Stop the Bleeding Before You Clean Up
Before you touch a single old transaction, separate your business money from your personal money. If you have been running everything through one checking account, open a dedicated business account today. Going forward, every business dollar flows through that account. This single change prevents the current year from becoming another mess you have to untangle next January.
Do not try to fix the past and the present at the same time. The past requires a methodical catch up process. The present requires a clean system that keeps new transactions organized. Trying to do both at once guarantees you finish neither.
Step Two: Gather Every Document Before You Categorize
Categorization requires context. You cannot assign a transaction to the correct expense account if you do not remember what it was for. Gather every document first, then categorize with the context in front of you. This order prevents guesswork and reduces errors.
Download every bank statement and every credit card statement for every account tied to your business for all twelve months. Pull your merchant processor reports if you accept card payments. Collect every 1099 you received from clients and platforms. Locate every receipt you can find, paper and digital.
Organize Documents by Month, Not by Type
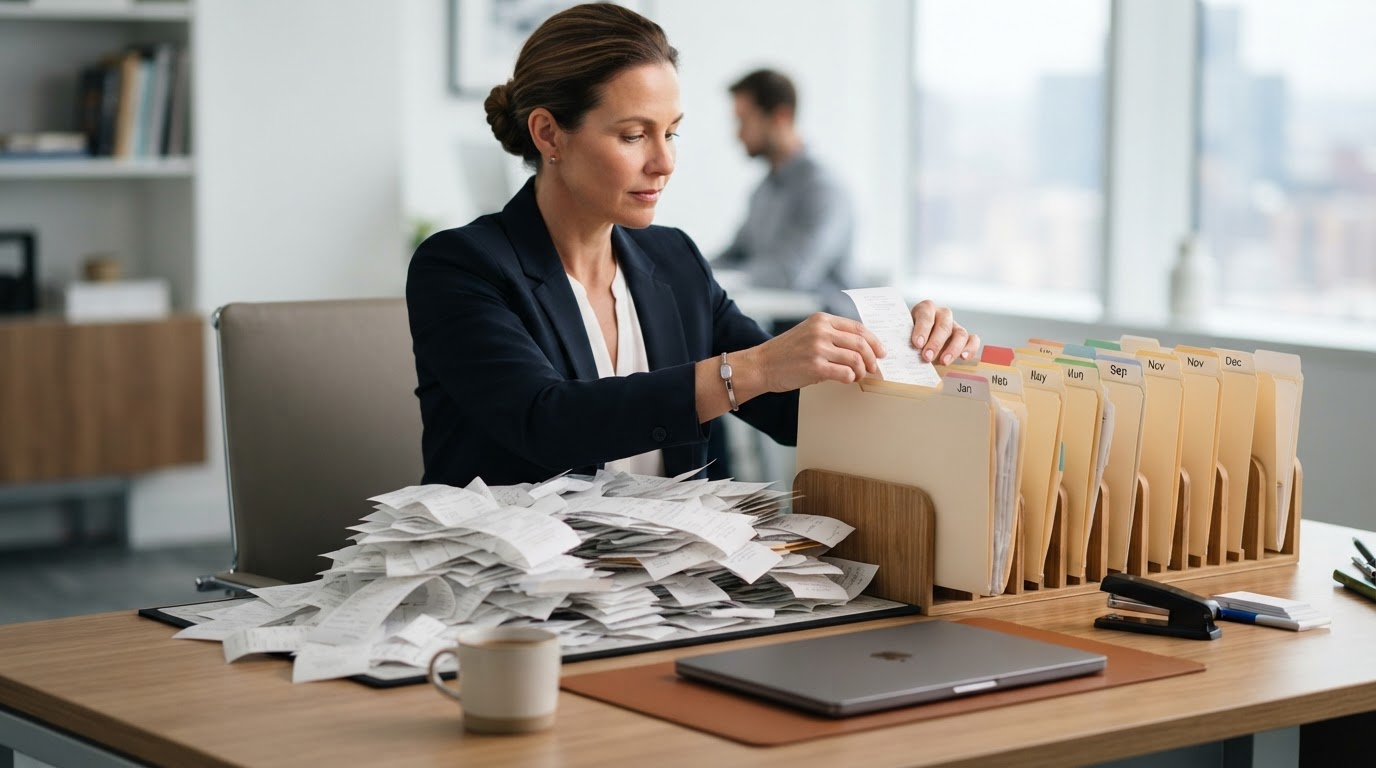
Sort your statements and receipts by month, not by category. January documents go in the January folder. February documents go in the February folder. This structure matters because you will rebuild your books one month at a time. When the documents for each month sit together, the categorization process moves quickly.
If you use cloud storage, create a folder for the tax year, then a subfolder for each month. Name your statement files clearly with the account and the period. A folder named 2025 Checking with files labeled 01-January through 12-December turns a chaotic pile into an organized archive you can actually work through.
Step Three: Rebuild Your Books One Month at a Time
Open your accounting software and start with January. Import or enter the transactions for that month from your bank statement. Categorize each one using the receipts and notes in your January folder. When the month is complete, reconcile it against the official bank statement. When the difference reaches zero, move to February.
This is the slowest part of the process. A full month of transactions can take several hours to categorize and reconcile properly. Resist the urge to rush. Every shortcut you take here becomes a liability on your tax return. Accuracy matters more than speed, especially when the IRS may compare your numbers against third party reporting.
Categorize With Your Tax Return in Mind
Every category you create should map directly to a line on your tax return. If you dump everything into a generic expense account, you lose the detail that lets you claim specific deductions. If you create too many narrow categories, your reports become unreadable and your return becomes a mess.
Aim for clear, meaningful categories that match the way the IRS structures business expenses. Meals, travel, office supplies, software subscriptions, contractor payments, and vehicle expenses each deserve their own account. When your categories align with your return, the tax filing process becomes a matter of reading your reports rather than reconstructing your year from memory.
Step Four: Digitize Every Receipt You Can Recover
Paper receipts fade within months. The thermal ink disappears and you are left with a blank slip that proves nothing. If you still have readable receipts, photograph them immediately using a receipt capture app or your accounting software mobile app. Digital receipts are searchable, permanent, and instantly accessible during an audit.
For receipts you have already lost, reconstruct the expense from your bank or credit card statement. The statement proves the transaction occurred and shows the amount and the vendor. It does not prove the business purpose, which is what the receipt provides. Document the business purpose in a note attached to the transaction in your software. A statement plus a written business purpose is weaker than a receipt, but it is far better than nothing.
Accept That Some Deductions Are Gone
Be honest with yourself. Some receipts are gone forever. Some transactions will remain uncategorized because you genuinely cannot remember what they were. Trying to force a deduction you cannot document creates a larger risk than the deduction is worth. An undocumented deduction disallowed in an audit costs you the tax plus penalties plus interest.
Accept the loss, categorize the transaction as best you can, and resolve to never let it happen again. The goal of a catch up is accuracy, not perfection. An accurate return with a few lost deductions is always better than an inflated return built on guesswork.
Step Five: Reconcile Every Account to the Penny
Reconciliation is the process of comparing your accounting software balance to your official bank statement. It confirms that every transaction was recorded, that no duplicates exist, and that nothing was missed. Reconciliation is not optional. It is the proof that your numbers are real.
Work through each month in order. You cannot reconcile March before you reconcile January and February, because the opening balance of each month depends on the closing balance of the month before it. When the reconciliation screen shows a remaining difference, do not force it to close. Hunt for the cause. The discrepancy is almost always a duplicate transaction, a missing fee, or a transaction dated in the wrong month.
Step Six: Generate and Review Your Financial Statements
Once every month is reconciled, generate your profit and loss statement for the full year. This report shows your total income, your total expenses, and your net profit. It is the foundation of your tax return. Review it carefully before you file.
Look at the numbers and ask whether they make sense. Is your net profit positive and reasonable for your industry? Do your expense ratios look appropriate? If something looks wrong, it probably is. This is your last chance to catch an error before it reaches your return and becomes a problem you have to explain to the IRS.
Check Your Balance Sheet for Structural Errors
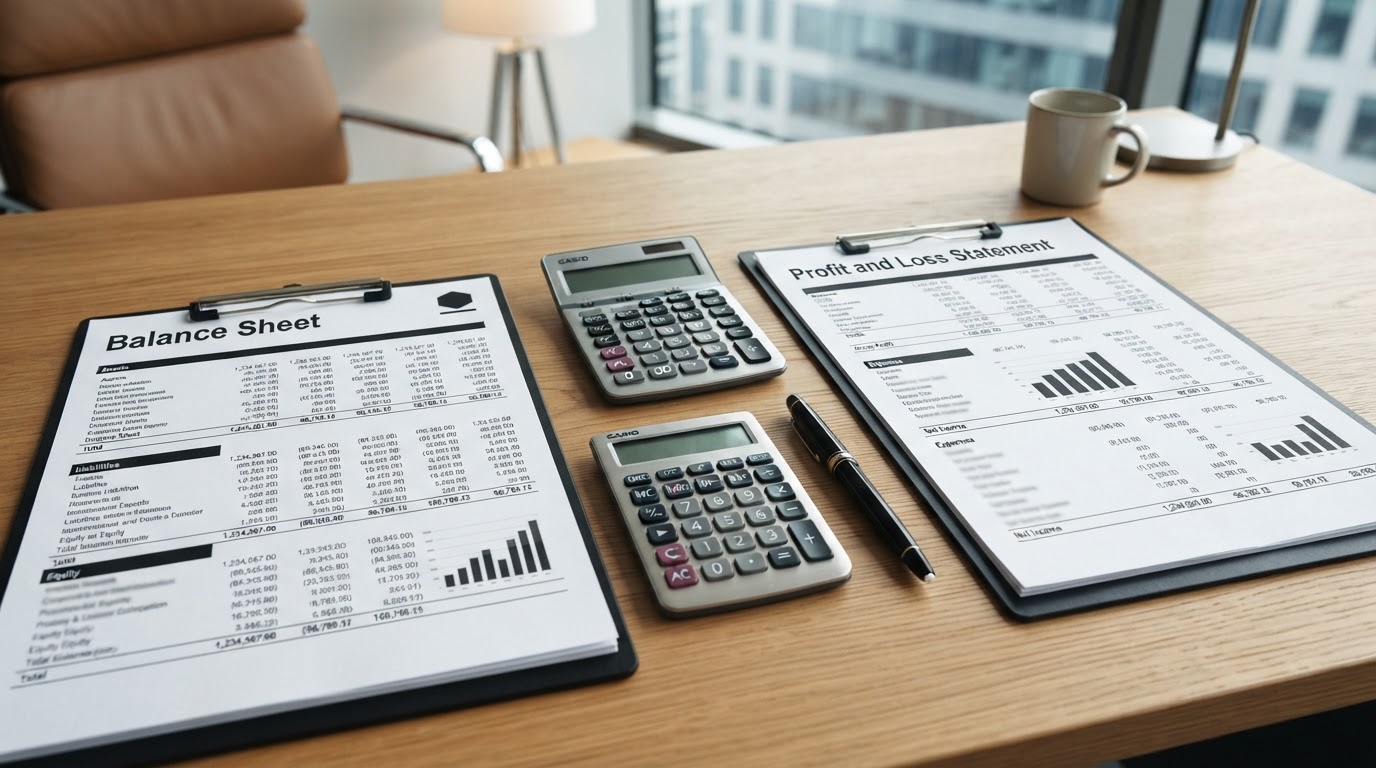
Your balance sheet must balance. Total assets must equal total liabilities plus equity. If that equation is off, something in your books is wrong, even if your profit and loss statement looks fine. Common balance sheet problems include negative accounts receivable, loan balances that never decrease, and equity accounts that do not reflect owner contributions and draws correctly.
These issues do not appear on a profit and loss statement, which is why you must review both reports together. A broken balance sheet signals deeper structural errors that can distort your tax return and create problems with lenders or investors who request your financial statements later.
Step Seven: File Your Return With Confidence
When your books are reconciled and your statements are reviewed, your tax return becomes a straightforward document. Your income matches your 1099s. Your expenses are categorized and documented. Your net profit is verified. You file knowing every number is defensible.
If you cannot complete the catch up before the deadline, file an extension. An extension gives you more time to file your return, but it does not give you more time to pay any tax you owe. Estimate your liability based on your best available numbers and send a payment with your extension request. This avoids the failure to pay penalty on the estimated amount.
Step Eight: Never Let This Happen Again
The catch up process is painful. Staying current is easy. Once your historical year is rebuilt, commit to a monthly bookkeeping habit. Reconcile every account once a month, within a week of receiving the statement. Categorize transactions while the context is fresh. Block a recurring time on your calendar and treat it like a client meeting you cannot cancel.
One hour a month prevents the kind of year end crisis that costs thousands in cleanup fees and missed deductions. The habit is the entire point. The businesses that survive tax season calmly are not the ones with the most automation. They are the ones with the discipline to maintain their books throughout the year.
Pay Quarterly Estimated Taxes Going Forward
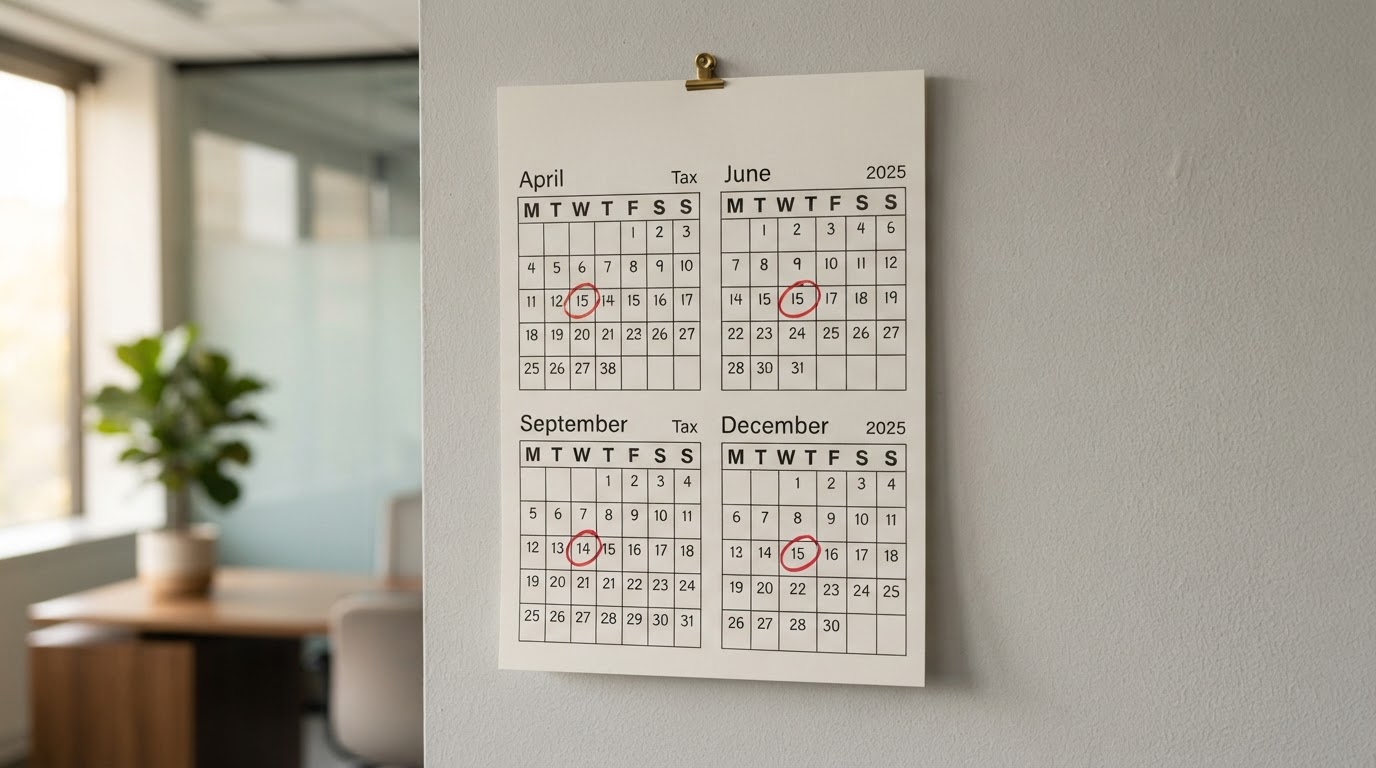
If you owed a significant tax bill this year, you likely need to pay quarterly estimated taxes going forward. The IRS requires you to pay tax as you earn income, not all at once at the end of the year. Underpaying throughout the year triggers penalties that compound with interest.
Base your quarterly estimate on your actual year to date profit, not a guess from last year. If your income is growing, your tax liability is growing too. Set aside a percentage of every payment you receive into a separate tax savings account. When the quarterly deadline arrives, the money is already saved and waiting.
Common Catch Up Mistakes to Avoid
- Rushing categorization to beat the deadline
- Forcing reconciliations to close with a remaining difference
- Dumping every expense into one generic account
- Claiming deductions you cannot document
- Skipping the balance sheet review entirely
- Filing late without estimating and paying what you owe
- Repeating the same neglect the following year
The Zion Approach and Strategy
We do not hand you a catch up checklist and disappear. We start by reconstructing every uncategorized month in your history, working backward from your most recent statement until every period balances to the penny. That historical cleanup gives you a clean foundation to file from instead of guessing your way through a year of forgotten transactions.
We then take over the monthly bookkeeping process for you. Every account, every credit card, every loan is reconciled within days of the statement closing. You never have to remember to do it, and you never have to wonder whether your numbers are real. We close each month with documentation you can hand to a lender, an investor, or the IRS without hesitation.
Our proactive approach means we calculate your quarterly estimated tax payments for you, based on your actual year to date profit, so you never underpay and never overpay. We review your profit and loss statement with you throughout the year and flag opportunities to reduce your tax burden before the year ends, not after.
When our clients grow, we grow too. Your financial clarity is the foundation of that growth. A business built on a year of neglected numbers is a business built on sand. We exist to move you onto solid ground and keep you there, month after month, year after year.
You Can Catch Up Alone, But You Do Not Have To
Every step in this guide is something you can do yourself. You can gather your statements, categorize your transactions, reconcile your accounts, and file your return. Many business owners do exactly that and survive tax season, exhausted but intact.
But an unshakeable financial foundation requires more than a one time catch up. It requires a dedicated partner who reconciles your accounts every month, reviews your statements for hidden errors, and guides your tax strategy throughout the year. The cost of a missed deduction, a late filing, or a year of neglected books always exceeds the cost of professional support.
When you are ready to stop dreading tax season and start building on a verified foundation, we are ready to help. Your business deserves books that are current, accurate, and defensible, every single month.