It's the End of the Year and My Books Are Completely Behind: Help
December arrives and your books are still sitting where you left them in March. The bank feeds have not been reconciled. The receipts are in a shoebox. Your accountant is already asking for a clean profit and loss statement and you have nothing to hand over. The solution is not a frantic weekend scramble. It is a structured, month by month recovery plan that rebuilds your books in layers and gets you to tax season with numbers you can actually defend.
Why Year End Turns Bookkeeping Into a Crisis
Bookkeeping procrastination follows a predictable pattern. You fall behind in February because of a busy quarter. March feels like a good time to catch up, but you never do. By June the gap is so large that opening the software feels worse than ignoring it. Then December arrives, and ignoring the problem is no longer an option.
The pressure at year end is real and specific. Your tax preparer needs accurate numbers to file on time. Your lender may require updated financial statements before January. Your own decision making suffers because you are operating blind, guessing at profitability based on your bank balance instead of real financial data.
The First Step Is a Full Diagnostic
Before you categorize a single transaction, you need to know exactly how far behind you are. Open your accounting software and identify the last month that was fully reconciled. That date is your starting point. Everything before it is clean. Everything after it is the work you need to complete.
Write down the gap in plain terms. If your last reconciliation was March, you have nine months of work ahead. Knowing the exact size of the problem removes the vague dread that makes the task feel impossible. A specific number of months is a project you can plan. A vague feeling of being behind is a paralysis trap.
What Your Diagnostic Must Capture
- The exact month your last reconciliation was completed
- The total number of unreconciled bank and credit card accounts
- The count of uncategorized transactions waiting in your feed
- Any accounts that were closed or opened during the gap
- Loans or lines of credit that need separate tracking
This list becomes your project scope. You will work through it item by item, account by account, until every line is resolved. The diagnostic takes an hour and saves you days of wasted effort later.
Gather Every Source Document Before You Start
The most common reason catch up work stalls is missing information. You sit down to categorize April, realize you cannot find the April bank statement, and abandon the entire effort. Gather every document you need before you touch a single transaction.
Log into every bank and credit card portal and download the statements for every month in your gap period. Export them as PDFs and save them in clearly named folders by month. If you use payment platforms like Stripe or PayPal, download those statements too. The goal is to have every source of truth sitting in front of you before the categorization work begins.
The Document Checklist for a Full Catch Up
- Monthly bank statements for every business checking account
- Monthly statements for every business credit card
- Payment processor statements from Stripe, PayPal, or Square
- Loan statements showing principal and interest breakdowns
- Receipts for any large or unusual purchases
- Payroll reports if you ran payroll during the gap
When every document is in place, the categorization work moves fast. You are no longer stopping and starting to hunt for a missing statement. You move through each month in a single uninterrupted flow.
Work One Month at a Time, In Order
The biggest mistake business owners make during catch up is jumping around between months. They categorize a few transactions in April, then skip to September because a receipt reminded them of a September purchase. This scattered approach guarantees errors and guarantees the project never finishes.
Instead, commit to a strict chronological order. Start with the first unreconciled month and do not move forward until that month is complete. Categorize every transaction. Reconcile the month against the bank statement. Confirm the ending balance matches. Only then do you advance to the next month.
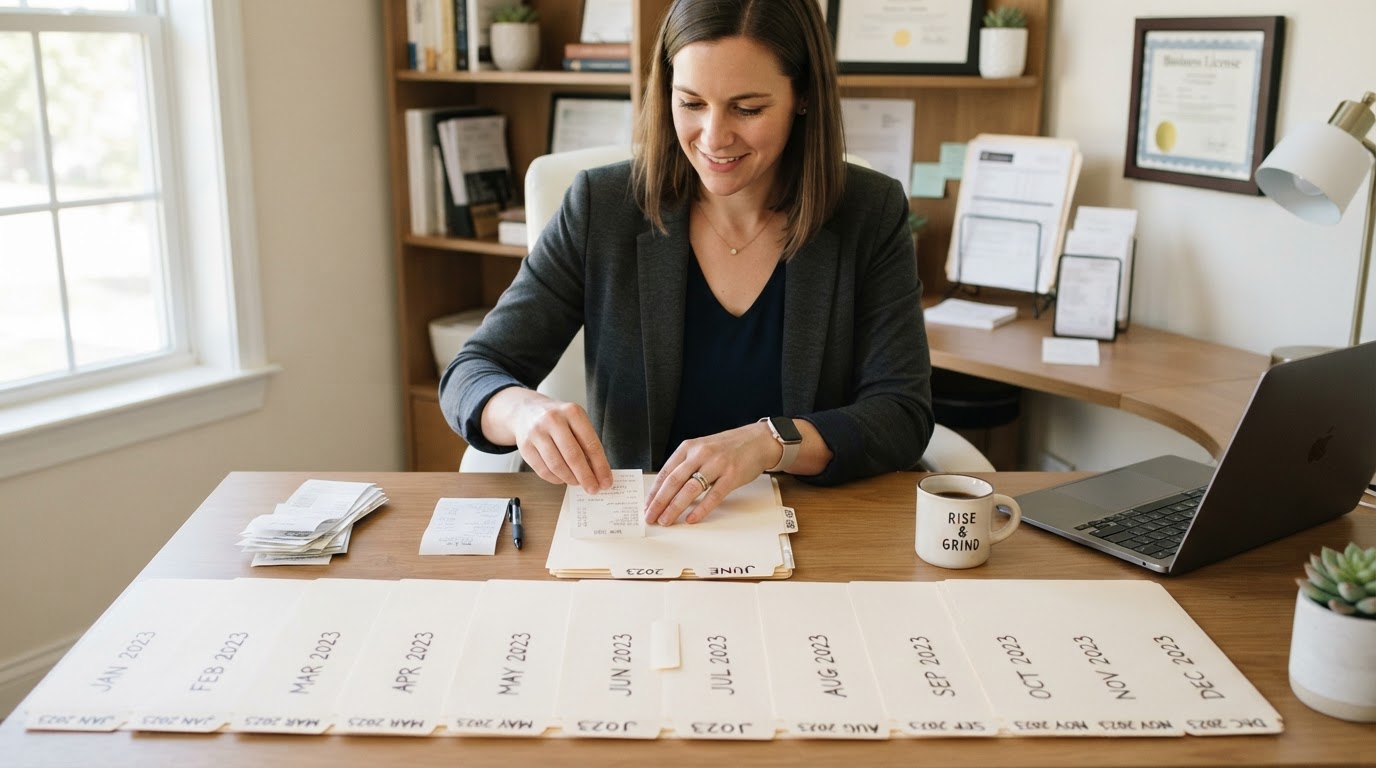
The Monthly Completion Standard
- Every transaction in the bank feed is categorized
- The bank reconciliation shows a zero difference
- Any missing transactions are added manually
- Any duplicates are identified and removed
- The month is marked reconciled and locked
This standard is non-negotiable. A month is either fully complete or it is not started. There is no partial credit in bookkeeping. A half reconciled month creates more confusion than a fully ignored one because it gives you false confidence in numbers that are still wrong.
Handle the Hard Transactions as They Come
During any catch up period you will encounter transactions you do not understand. A large transfer between accounts. A payment to a vendor you do not recognize. A refund that looks like income. These transactions are where most business owners freeze and abandon the project.
The solution is to flag every uncertain transaction and keep moving. Create a single category called Review Later and assign anything unclear to it. Do not stop your momentum to research a single mystery transaction. Finish the month, then return to the flagged items with fresh focus and your source documents in hand.
Common Mystery Transactions and Their Real Meaning
- A transfer between your own accounts, not income or expense
- A merchant refund that reduces an expense, not new income
- A loan payment split between principal and interest
- A personal expense paid from the business account
- A vendor payment under a different legal name
Each of these has a specific correct treatment. Guessing at them during a rushed catch up creates errors that propagate into your tax return. Flagging and revisiting them protects the integrity of your entire financial record.
Reconcile Every Account Before You Trust a Single Number
Categorization is only half the work. Reconciliation is the proof that your categorization is correct. Reconciliation is the process of confirming that the transactions in your software match the transactions on your bank statement, down to the cent. Without reconciliation, your profit and loss statement is a guess.
Run the reconciliation tool for each month of each account. The software will show you the cleared balance and the statement balance. When they match, the month is reconciled. When they do not match, you have a discrepancy to find. Do not skip this step under any time pressure. A reconciled book is the only book worth filing a tax return from.
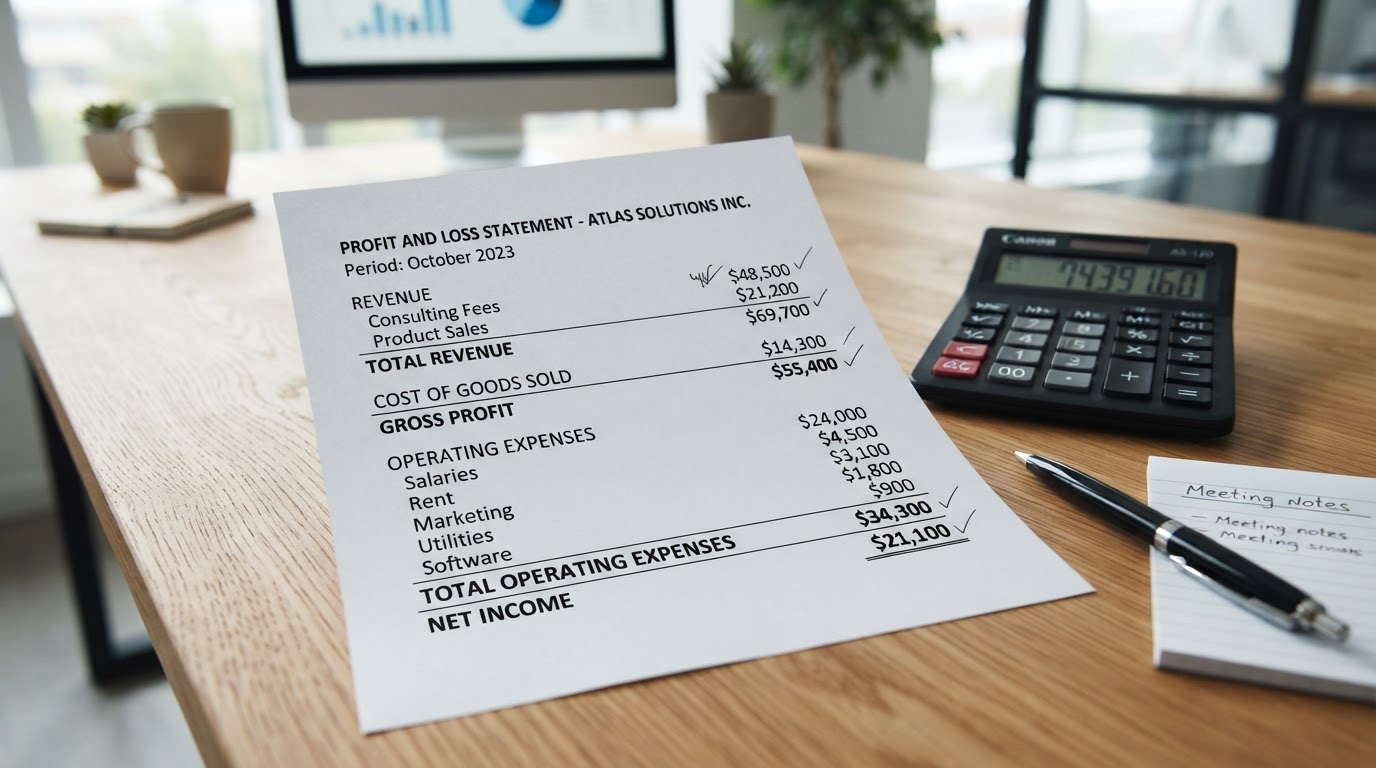
What Reconciliation Catches at Year End
- Transactions recorded in the wrong accounting period
- Bank fees and interest that were never logged
- Duplicate entries from manual and automatic imports
- Transposed digits that flip a number silently
- Missing deposits that never made it into the books
Each of these errors distorts your profit. A single missed deposit can make a profitable month look like a loss. A duplicate expense can make a healthy margin look like a crisis. Reconciliation is what separates real financial data from a number that merely looks plausible.
Generate Your Financial Statements Only After the Work Is Done
The temptation at year end is to pull a profit and loss statement the moment the panic hits and try to make decisions from it. Do not. A profit and loss statement built on unreconciled, uncategorized data is worse than no statement at all because it gives you false confidence.
Wait until every month is categorized and reconciled. Then generate your profit and loss statement and your balance sheet. Review them for obvious errors. Does your net income look reasonable for the year? Does your balance sheet balance? Does your equity account reflect owner contributions and draws correctly? Only when these statements hold up to scrutiny are you ready to hand them to a tax preparer.
The Tax Season Countdown and What It Means
Once your books are clean, the tax filing process becomes straightforward. Your tax preparer takes your reconciled profit and loss statement and your balance sheet and builds your return from numbers they can trust. There are no surprises, no last minute discoveries, and no emergency cleanup invoices.
The businesses that file early and stress free are the ones that finished their bookkeeping before January. The businesses that file extensions and scramble in March are the ones that ignored their books all year. The difference is not luck or size. The difference is whether the catch up work was completed before the deadline pressure arrived.
The Zion Approach and Strategy
At Zion Accounting and Tax, we specialize in year end catch up work without judgment. When a client comes to us in December with nine months of untouched books, we do not lecture them. We run a full diagnostic, identify the exact gap, and build a recovery plan that fits the timeline they have left.
We gather every source document on their behalf, including bank statements, credit card statements, and payment processor exports. We categorize every transaction month by month in strict chronological order. We reconcile every account against the official statements. We flag every uncertain transaction and resolve it with the client before we lock the month. The client never has to guess whether a number is right because we prove it with a completed reconciliation.
Our strategy is proactive, not reactive. Once the catch up is complete, we keep the client current on a monthly schedule so this crisis never repeats. We run quarterly tax planning sessions so there are no surprises at year end. When our clients grow, we grow too, and our clients grow fastest when their financial foundation is unshakeable. We do not just record your financial history. We actively guide your financial future.
You Can Catch Up Alone, But You Do Not Have To
Every step in this guide is something you can attempt on your own. You can run the diagnostic, gather the statements, categorize the transactions, and reconcile the accounts without help. Plenty of business owners try. Most of them run out of time because the volume of work is far greater than they estimated, and the deadline pressure forces them into rushed errors that cost more to fix later.
An unshakeable financial foundation requires more than good intentions. It requires a dedicated partner who knows your business, who reviews your numbers proactively, and who catches the errors you cannot see. The businesses that enter tax season calm and prepared are the ones that stopped treating bookkeeping as a solo chore and started treating it as a strategic advantage. When your foundation is solid, your potential is limitless.
Trusted by small businesses and entrepreneurs who refuse to let a year of neglected books dictate their financial future.
Related Insights
View all insights
When Do Spreadsheets Stop Working for Small Business Bookkeeping?
Spreadsheets feel like a smart, low cost way to track your business finances in the beginning. That control is an illusion that shatters the moment your transaction volume passes a specific threshold.
I Haven't Done My Books in Six Months: What to Do Now
Six months of untouched books is a solvable problem. The solution is not a frantic weekend scramble but a structured month by month recovery plan that rebuilds accuracy in layers.
Two Years Behind on Bookkeeping and Tax Season Is Coming
Two years of untouched books feels like a death sentence for your finances. The reality is far more manageable than the panic suggests with a structured year by year reconstruction plan.