Two Years Behind on Bookkeeping and Tax Season Is Coming
Two years of untouched books feels like a death sentence for your business finances. The reality is far more manageable than the panic suggests. A structured, year by year reconstruction plan brings even the most neglected ledgers back to full compliance before the tax deadline arrives.
Many business owners discover their bookkeeping gap only when a tax notice arrives or a lender requests financial statements. The moment of realization is paralyzing. Two full calendar years of transactions sit unrecorded, unreconciled, and completely disorganized.
The instinct is to hide from the problem or to attempt a frantic, sleepless weekend of brute force data entry. Both reactions make the situation worse. Fiscal integrity demands a methodical recovery built on verified source documents, not guesswork. This guide walks through the exact framework we use to rebuild two years of neglected books from scratch.
The True Cost of Two Years of Neglect
Every month your books sit untouched, you lose financial visibility. After twenty four months, you are operating entirely blind. You cannot confirm whether your pricing covers your true costs. You cannot identify which clients drain your margins. You cannot prove your profitability to a bank, an investor, or the IRS.
Two years of unrecorded expenses means two years of potentially missed deductions. The IRS does not reward disorganization. If you cannot substantiate a business expense with a receipt or a bank record, you forfeit the deduction. A neglected ledger quietly inflates your taxable income and hands the government money you legally could have kept.
Beyond taxes, the gap creates cascading compliance failures. Unfiled quarterly payroll returns accumulate penalties monthly. Missing 1099 filings trigger separate fines per contractor. The longer the gap persists, the more expensive the cleanup becomes. Inaction is the most expensive choice you can make.
Why the Panic Weekend Always Fails
Business owners who panic tend to import two years of bank data into their software and accept every automatic categorization suggestion. This creates a false sense of accomplishment. The transactions appear in the system, but they are rarely accurate.
A single misapplied rule can misclassify an entire year of transactions. You finish your marathon weekend feeling relieved, only to discover during tax preparation that your profit and loss statement is worthless. Sloppy speed always costs more than deliberate accuracy in accounting. The cleanup must happen in layers, not in a single sprint.
Phase 1: Gather Every Source Document
Before you touch your accounting software, collect every financial document your business produced over the past two years. This is your raw material. You cannot reconstruct what you cannot see. Missing statements create permanent gaps that force you to estimate, and estimates invite IRS scrutiny.
Log into every bank, credit card, loan, and payment processor account. Download the monthly statements as PDFs. Export the transaction histories as CSV files. Organize them in folders sorted by year, then by month, then by account. This step alone removes most of the anxiety because the information is finally visible and contained.
The Complete Two Year Document Checklist
- Business checking and savings statements for all 24 months
- All business credit card statements
- Loan and line of credit statements
- PayPal, Stripe, and Square settlement reports
- Payroll reports and quarterly tax filings
- Contractor payment records and 1099 copies
- Receipts for major equipment and vehicle purchases
- Mileage logs or vehicle usage records
- Prior year tax returns and depreciation schedules
- Any IRS or state tax notices received
Phase 2: Establish Your Starting Point
You cannot rebuild two years of records without knowing exactly where the oldest unreconciled period began. Identify the precise opening balance of every account on the first day of the oldest month you need to reconstruct. This number anchors every reconciliation that follows.
Pull the balance directly from the bank statement, never from memory or from your software. If your accounting software shows a different opening balance than your statement, correct the software first. A wrong starting balance guarantees that every subsequent reconciliation will fail by the exact same amount.
If you filed tax returns for the prior year, use the ending balances from those returns as your anchor. The prior year return is your verified baseline. Everything you rebuild must tie back to that number. If it does not, you have an error that must be resolved before you move forward.
Phase 3: Reconstruct Month by Month
Resist every urge to import all twenty four months at once. Import one month, categorize it completely, and reconcile it before moving to the next. This sequential approach contains errors. If something goes wrong in March of the first year, you catch it immediately instead of discovering it eighteen months later.
During categorization, disable the automatic rules temporarily. Review every transaction manually. Two years of data contains unusual purchases, one time expenses, and personal transactions mixed in. Automatic rules cannot distinguish between a recurring software subscription and a similar sized personal purchase. Manual review is slower, but it is the only path to accuracy.
Categorization Standards That Prevent Errors
- Separate cost of goods sold from general overhead
- Isolate owner draws and personal expenses immediately
- Flag every fixed asset purchase for depreciation review
- Match every deposit to a specific customer invoice
- Reconcile each account to the penny before advancing
- Document the business purpose for every unusual charge
Phase 4: Reconcile Every Account to the Statement
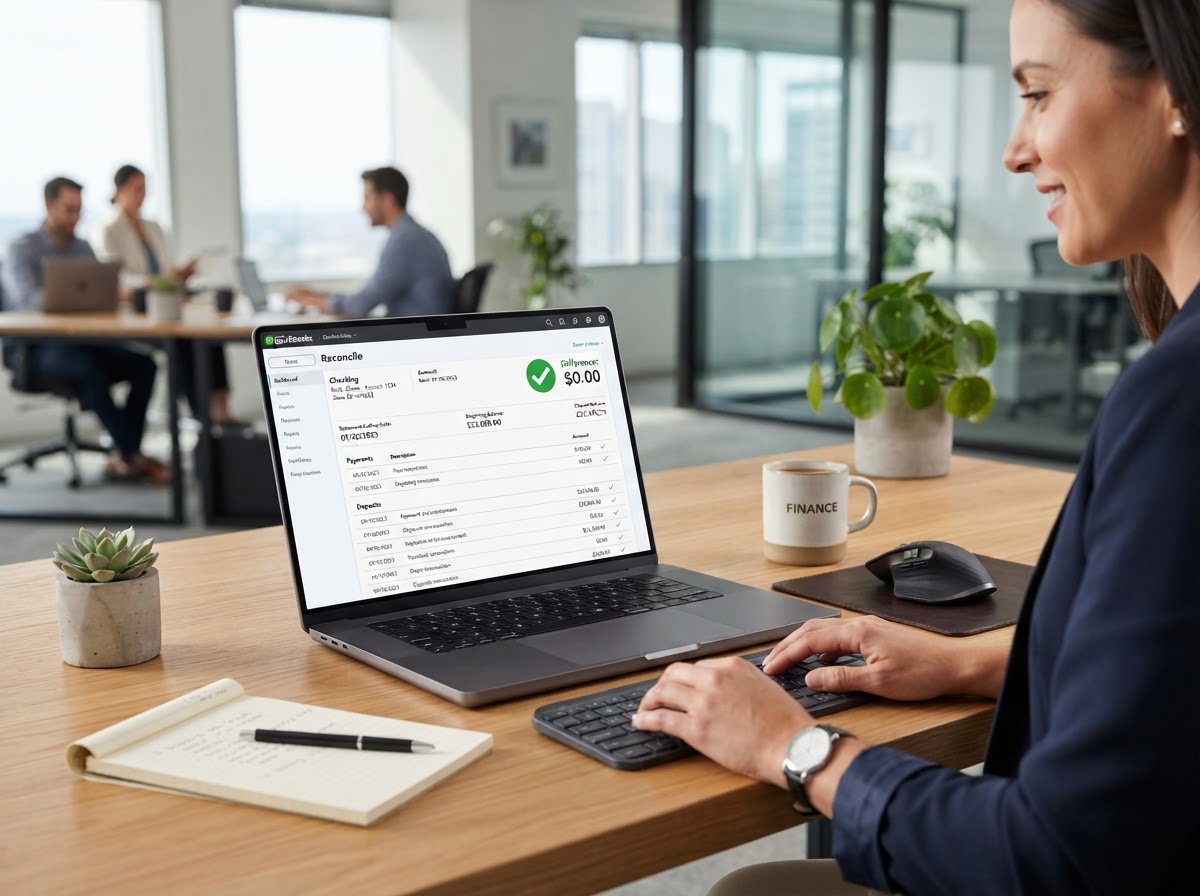
Reconciliation is the single most important step in a two year cleanup. It is the process of confirming that every transaction in your software matches the official bank statement for that month. Without reconciliation, your books are just a collection of unverified numbers.
Start with the oldest unreconciled month. Compare your software ending balance to the statement ending balance. If they match, mark the month reconciled and advance. If they do not match, you must find the discrepancy before moving forward.
Common discrepancies include duplicate transactions, missing fees, unrecorded transfers between accounts, and transactions recorded on the wrong date. Hunt down every difference to the exact cent. A reconciliation that is off by even one dollar is not complete. Fiscal integrity means your books match your bank exactly, every single month.
Phase 5: Separate Personal and Business Transactions
Two years of neglected books almost always contain commingled personal and business expenses. Owners paid for business supplies with personal cards. They paid personal bills from the business account. These transactions must be identified and reclassified before your financial statements mean anything.
For business expenses paid personally, record them as owner contributions or shareholder loans, depending on your entity structure. For personal expenses paid from the business account, record them as owner draws or distributions. This separation is not optional. Commingled funds destroy your audit defense and jeopardize your liability protection.
If the commingling is severe, consult a professional immediately. Extreme cases can pierce the corporate veil of an LLC or corporation, exposing your personal assets to business creditors. The cleanup must be thorough and documented.
Phase 6: Review Fixed Assets and Depreciation
Two years of operations likely included major equipment purchases, vehicle acquisitions, or property improvements. These are fixed assets, not regular expenses. They must be capitalized and depreciated over their useful life according to IRS rules.
Many business owners incorrectly write off the full purchase price of a truck or a piece of machinery in the year they buy it. While Section 179 and bonus depreciation allow accelerated writeoffs in some cases, the election must be made properly on your tax return. Simply expensing a capital asset in your bookkeeping software creates a mismatch that triggers IRS questions.
Review your fixed asset list against your purchase receipts. Confirm that every asset over the capitalization threshold is recorded properly. Verify that depreciation is calculated correctly for both book and tax purposes. Errors here compound over years and become extremely expensive to unwind.
Phase 7: Prepare the Back Tax Returns
Once your books are reconstructed and reconciled for both years, you can prepare the back tax returns. This is the step most owners fear, but it is only possible because of the work you just completed. Clean, reconciled books make tax preparation straightforward.
File the oldest year first. The IRS processes returns chronologically, and your second year depends on the ending balances of the first. If you owe taxes for the prior year, pay what you can immediately to stop the penalty and interest accumulation. Then set up a payment plan for the remainder if needed.
Filing voluntarily, even years late, is always treated more leniently than waiting for the IRS to find you. The failure to file penalty is ten percent per month, capped at five times the tax owed. The failure to pay penalty is far smaller. Filing stops the failure to file penalty from growing further.
Phase 8: Address Payroll and 1099 Gaps
If you had employees during the gap period, you likely missed quarterly payroll tax filings. Form 941 returns must be filed for every quarter you operated payroll. State payroll returns and unemployment filings have their own separate deadlines.
File the missing payroll returns as quickly as possible. The IRS trust fund penalty applies to unpaid employee withholding, and it is assessed personally against responsible owners. This penalty cannot be discharged in bankruptcy. Payroll tax gaps are the most dangerous consequence of neglected bookkeeping.
For contractors paid over six hundred dollars per year, verify that 1099 forms were issued. If they were not, file them late voluntarily. The penalty per missing 1099 increases the longer you wait. Voluntary late filing reduces the penalty significantly compared to an IRS initiated discovery.
Common Mistakes During a Two Year Cleanup
Even motivated business owners make predictable errors during a long reconstruction. Recognizing these traps in advance saves weeks of rework and prevents costly tax mistakes.
Estimating Instead of Verifying
When a statement is missing, owners estimate the transactions based on memory. Estimates create audit exposure. Always obtain the actual statement from the bank. Most institutions retain up to seven years of records online. If your access is closed, request archived statements directly from the institution.
Ignoring the Prior Year Tax Return
The ending balances on your last filed tax return are your verified starting point. If your reconstructed books do not tie to those numbers, you have an error. Never proceed past a mismatch. Resolve it first, then continue the reconstruction.
Forgetting to Close the Books
Once a year is fully reconciled and the tax return is filed, close the books in your accounting software. Closing prevents accidental changes to a period you already reported to the IRS. An open prior year invites silent edits that create new discrepancies between your books and your filed return.
The Zion Approach and Strategy
At Zion Accounting and Tax, we have rebuilt dozens of two year bookkeeping gaps without judgment. We do not lecture our clients about the past. We focus entirely on building a clean, verified foundation that moves the business forward.
We start every reconstruction with a secure document collection process. We pull statements directly from your financial institutions when access is available, eliminating the risk of missing records. We then rebuild your books month by month, reconciling every account to the exact penny before we advance to the next period.
We separate personal and business transactions meticulously. We review every fixed asset for proper depreciation treatment. We prepare and file your back tax returns, missing payroll forms, and late 1099s. We negotiate payment plans with the IRS when balances are owed, and we pursue penalty abatement wherever eligibility allows.
Once the cleanup is complete, we transition you to a proactive monthly bookkeeping cadence. We reconcile your accounts every single month so you never face a gap this large again. We review your numbers quarterly to identify tax saving opportunities before the year ends. Because when our clients grow, we grow too. Your financial foundation must be unshakeable for that growth to last.
Rebuild Your Foundation Before the Deadline
You can attempt to reconstruct two years of books alone, and with enough time you might succeed. But an unshakeable financial foundation requires a dedicated partner who knows exactly which documents to pull, which balances to verify, and which tax forms to file. The cost of a single missed deduction or a single misclassified asset far exceeds the cost of professional help. Stop carrying the weight of two years of neglect. Let us rebuild your books on solid ground so you can face tax season with complete confidence.
Ready to rebuild your books?
Stop dreading the gap. Let us reconstruct your books and file your back taxes with complete confidence.
Related Insights
View all insights
I Haven't Done My Books in Six Months: What to Do Now
Six months of untouched books is a solvable problem. The solution is not a frantic weekend scramble but a structured month by month recovery plan that rebuilds accuracy in layers.
My Books Are a Complete Mess: Where to Even Start Cleaning Up
Many business owners open their accounting software, see hundreds of uncategorized transactions, and immediately close it. The mess feels so enormous that paralysis sets in.
What to Do When You Have Mixed Personal and Business Expenses for Months
Many business owners fall into the trap of paying for business expenses with a personal credit card. They assume they will sort it out later when they have more time. But months go by and the financial records become completely entangled.