How to Separate Personal and Business Expenses After Years of Mixing Them
You started your business with a single debit card and the best of intentions. You promised yourself you would keep things separate. Then a client meeting ran late, you swiped your personal card for office supplies, and the line between business and personal vanished. Years later, your books are a tangled web of commingled funds that makes tax season a nightmare. The solution is not to start over. The solution is a structured separation process that untangles the past while building a clean wall for the future.
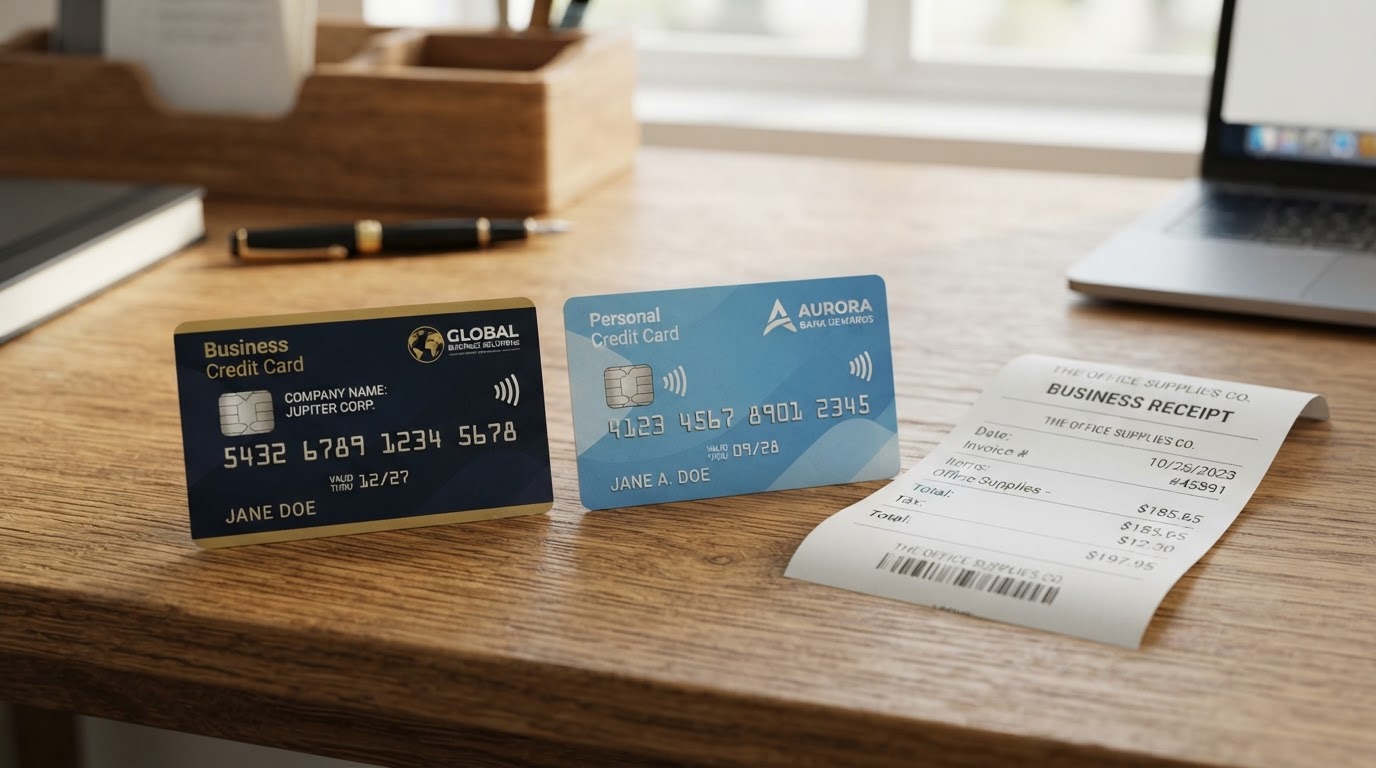
Why Commingled Funds Are a Serious Problem
Mixing personal and business expenses is not just a bookkeeping annoyance. It is a legal and financial liability that grows more dangerous every year you ignore it. The IRS requires business owners to keep separate records for a reason. When your accounts are tangled, you lose the ability to prove which expenses are legitimate business deductions.
If you are ever audited, the burden of proof falls on you. You must demonstrate that every deduction was a legitimate business expense. When your personal grocery runs and business supply purchases live in the same account, that proof becomes nearly impossible to produce. The IRS can disallow deductions entirely, which means you pay the tax plus penalties plus interest.
Beyond the IRS risk, commingled funds destroy your ability to understand your business. You cannot measure true profitability when personal spending inflates your expense categories. You cannot make informed growth decisions when your numbers are contaminated. The foundation of fiscal integrity starts with clean separation.
The Real Cost of Ignoring the Problem
Many business owners underestimate the financial damage of commingled funds. The costs compound silently until they become impossible to ignore. Here is what actually happens when you delay the cleanup.
- Lost deductions you cannot substantiate under audit
- Higher tax preparation fees from manual sorting
- Pierced corporate veil for LLC and S Corp owners
- Inaccurate financial statements driving bad decisions
- Hours wasted reconstructing transactions each quarter
- Increased audit risk from inconsistent reporting patterns
Step One: Open a Dedicated Business Bank Account
The first physical action in the separation process is opening a business checking account that is used exclusively for business transactions. This account becomes the new financial home for your business. Every dollar of business revenue flows in, and every dollar of business expense flows out.
If you operate as an LLC or corporation, this step is not optional. It is a legal requirement to maintain your liability protection. When you commingle funds in a formal entity, a court can pierce the corporate veil and hold you personally liable for business debts. The separation you create now protects your personal assets in the future.
Choosing the Right Account Type
A business checking account is the minimum. You should also consider a business savings account for tax reserves and a business credit card for expense tracking. The goal is to create a closed financial system where every transaction is clearly business related.
When you apply, bring your Employer Identification Number, your formation documents, and your business license. Most banks offer business accounts with low or no monthly fees if you maintain a minimum balance. The small effort of opening the account saves you thousands in accounting cleanup costs later.
Step Two: Get a Dedicated Business Credit Card
A business credit card is one of the most powerful tools for clean bookkeeping. Every transaction generates a digital record with a merchant name, date, and amount. At the end of the month, you have a complete statement that serves as a secondary source of documentation for your expenses.
Choose a card that integrates with your accounting software. When your credit card feeds directly into QuickBooks Online, you eliminate manual data entry entirely. The transactions appear automatically, and you simply categorize them. This single integration saves hours of bookkeeping time every month.
Never use this card for personal purchases. The moment you do, you recreate the exact problem you are trying to solve. If you need to make a personal purchase, use your personal card. The discipline of keeping the cards separate is the discipline that protects your books.
Step Three: Rebuild Your Chart of Accounts
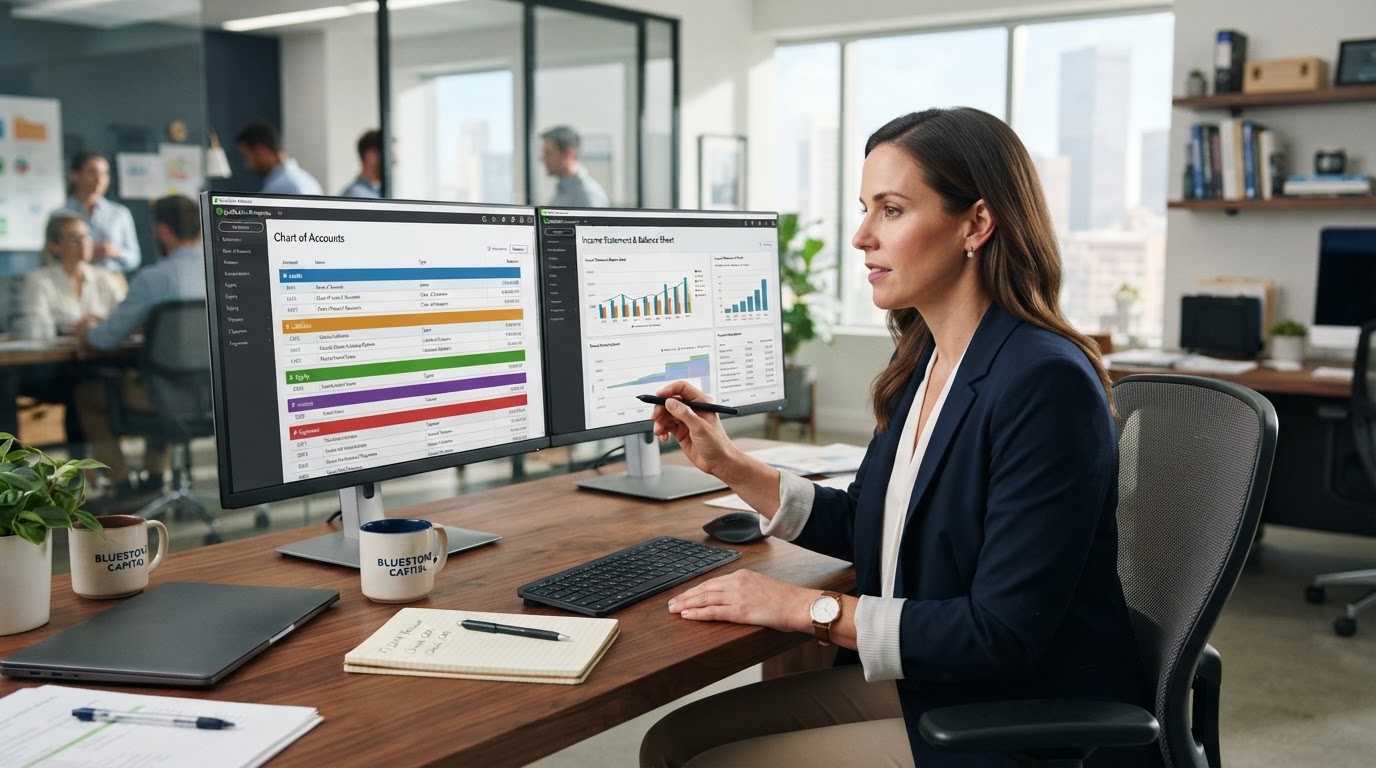
Your chart of accounts is the structural backbone of your bookkeeping system. When personal and business expenses are mixed, the chart of accounts becomes corrupted with misclassified transactions. Rebuilding it properly ensures every future transaction lands in the right place.
Start With Clean Parent Categories
A clean chart of accounts uses broad parent categories with specific subcategories underneath. Avoid the temptation to create dozens of hyper specific accounts. Too many accounts create confusion and increase the chance of misclassification.
- Income: sales revenue, service revenue, interest income
- Cost of goods sold: materials, direct labor, subcontractors
- Operating expenses: rent, utilities, software, marketing
- Payroll expenses: wages, payroll taxes, benefits
- Owner equity: owner contributions, owner draws
Create an Owner Equity Account
One of the most important accounts you will create is an owner equity or owner draw account. This account is the proper home for any personal expense you paid with business funds, or any business expense you paid with personal funds. Instead of forcing a transaction into a business expense category where it does not belong, you record it as an owner draw or an owner contribution.
This approach keeps your business expense categories clean and accurate. It also creates a clear record of how much money you have moved between personal and business accounts, which is essential for tax preparation and entity compliance.
Step Four: Digitize Every Receipt
Paper receipts fade, get lost, and create physical clutter. Digital receipts are searchable, permanent, and instantly accessible during an audit. The transition from paper to digital is one of the highest value changes you can make in your bookkeeping system.
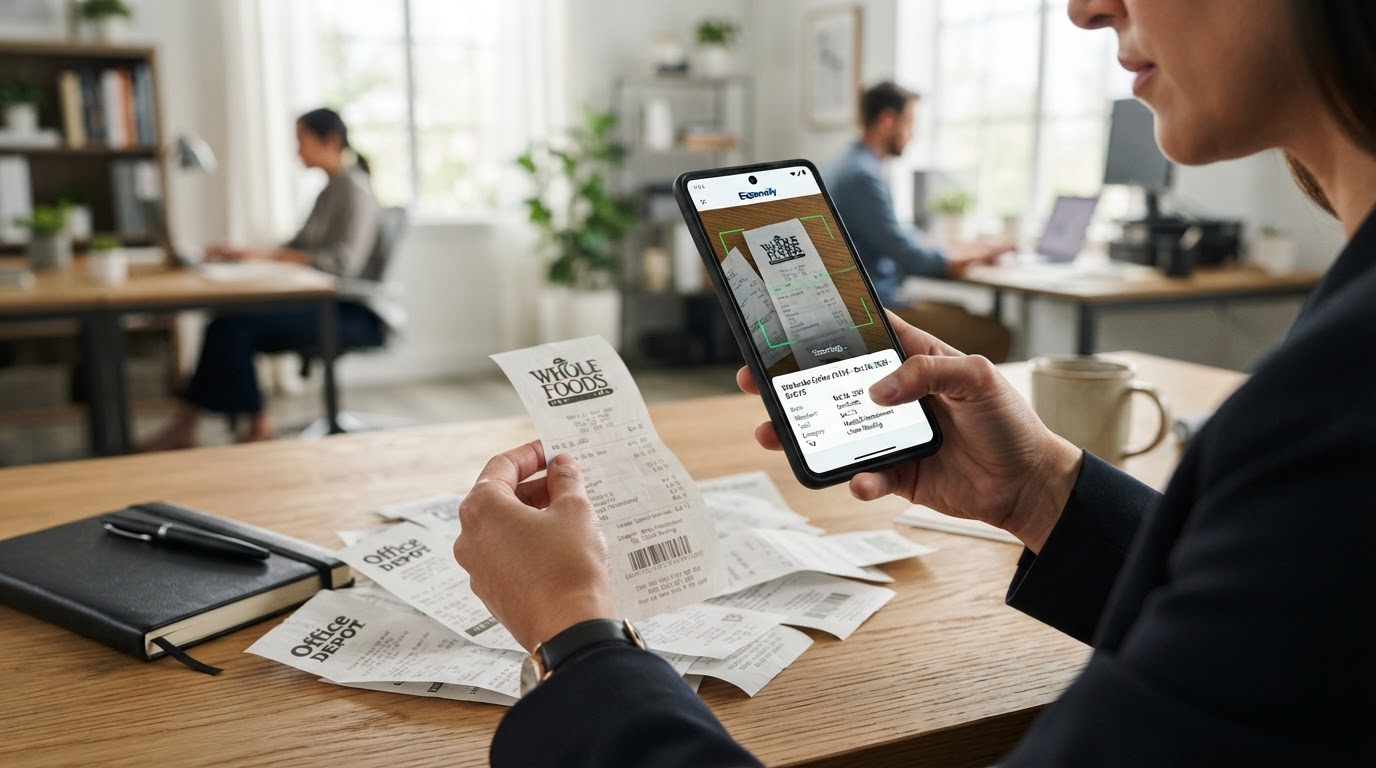
Use a receipt scanning app that integrates with your accounting software. When you snap a photo of a receipt, the app extracts the merchant, date, amount, and category. The digital receipt attaches directly to the transaction in your books. You never have to touch that piece of paper again.
Make scanning a daily habit. The longer you wait, the more receipts you accumulate, and the more likely you are to lose critical documentation. Five minutes a day prevents a five hour weekend scramble at the end of the month.
Step Five: Handle the Historical Mess
Opening new accounts solves the future. You still have to untangle the past. This is the step that causes the most anxiety, but a structured approach makes it manageable. The goal is to reclassify every commingled transaction in your historical records without fabricating any numbers.
Export and Sort Your Old Statements
Start by exporting your bank and credit card statements for the period you need to clean up. Most financial institutions allow you to export to a CSV file. Open the file in a spreadsheet and sort by merchant name. This sorting reveals patterns that make classification faster.
Create three columns: Business, Personal, and Unsure. Go through each transaction and assign it to a column. The ones you are confident about move quickly. The ones you are unsure about get flagged for a deeper review. Do not guess. A wrong classification is worse than a delayed one.
Record Owner Transactions Properly
For every personal expense you find in your business account, record it as an owner draw. For every business expense you find in your personal account, record it as an owner contribution. This treatment keeps your business expense categories clean while accurately reflecting the movement of money.
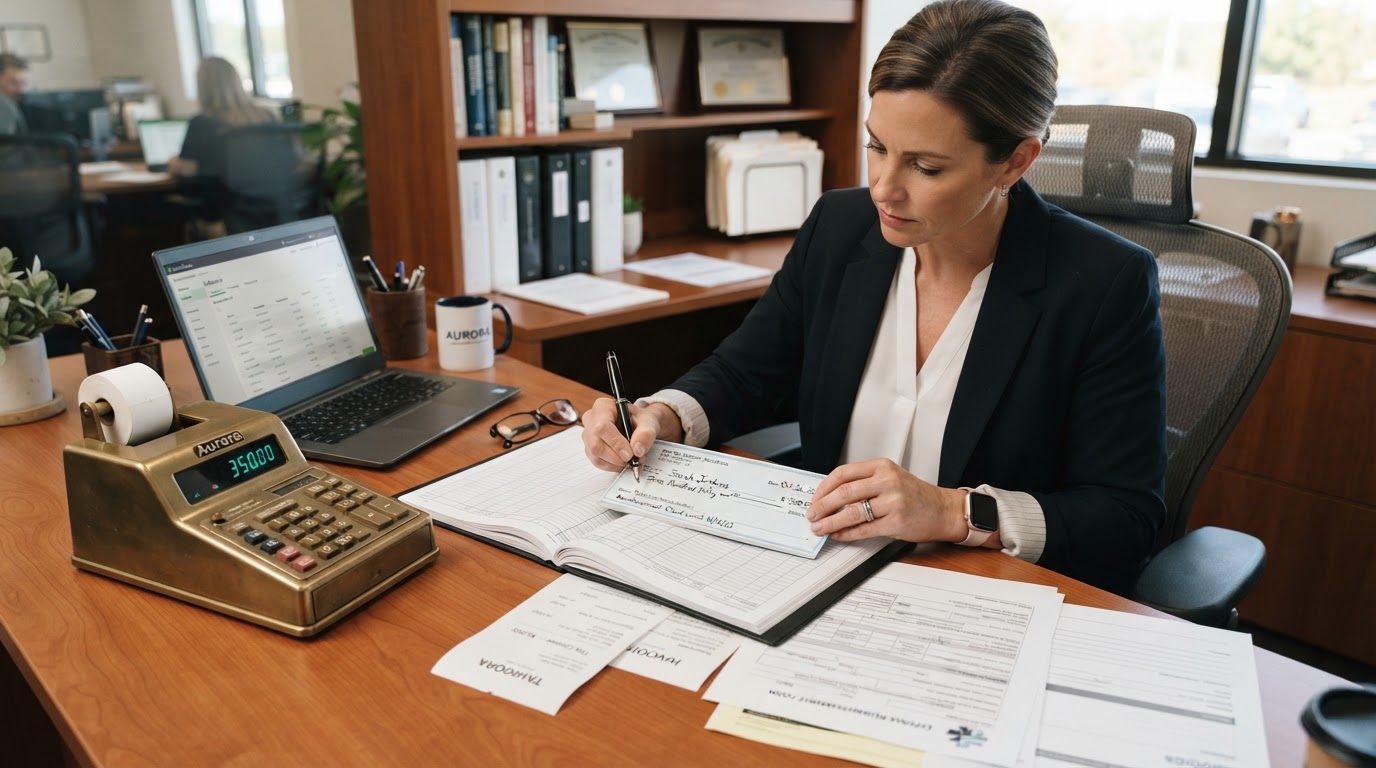
If you paid for a large business expense with personal funds, you may need to formally reimburse yourself from the business account. This reimbursement creates a clean paper trail that shows the expense moving from personal to business. Document the reimbursement with a memo and keep the original receipt.
Step Six: Reconcile Every Account Monthly
Reconciliation is the process of comparing your accounting records to your bank and credit card statements to ensure they match. It is the single most important habit for maintaining clean books after you have separated your accounts. Monthly reconciliation catches errors early, before they compound into major problems.
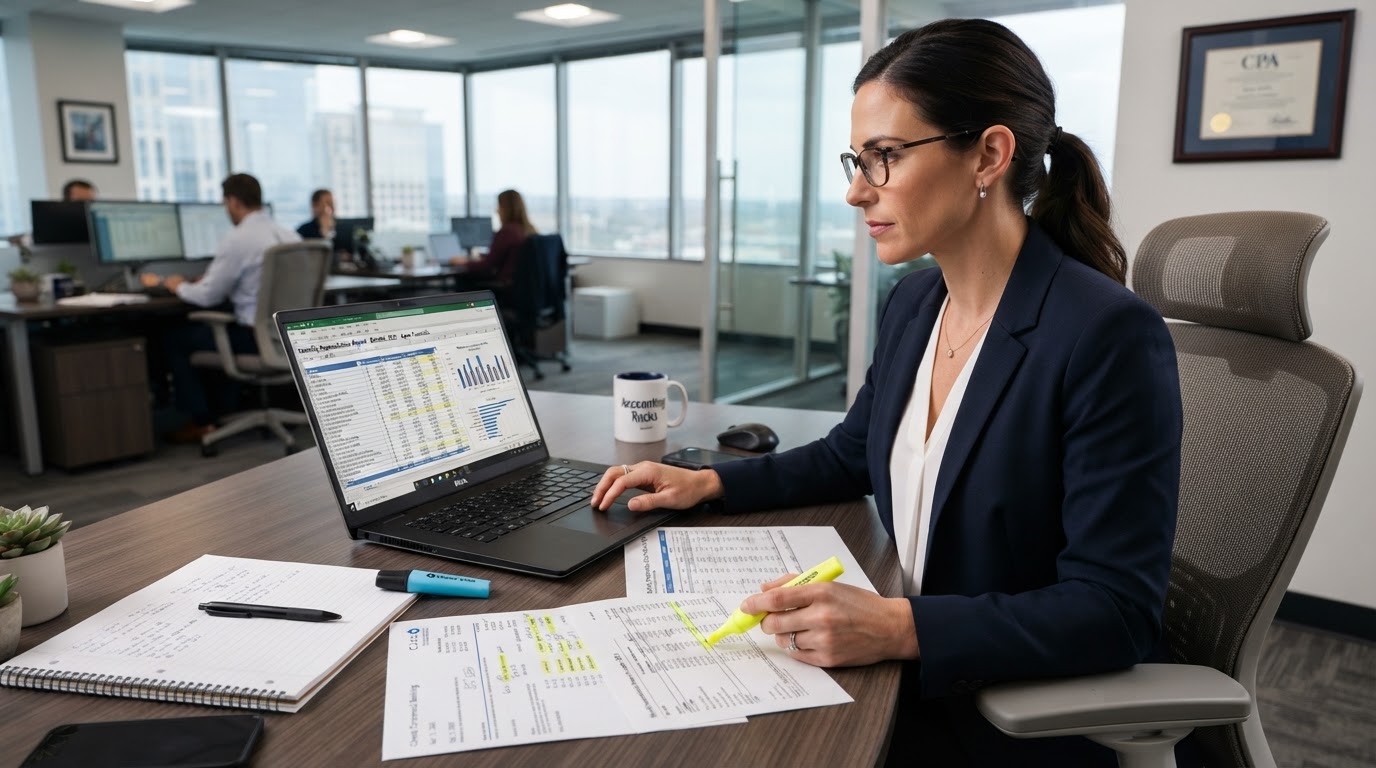
When you reconcile monthly, you work with a small, manageable set of transactions. When you reconcile quarterly or annually, the volume becomes overwhelming and errors hide easily. A monthly cadence keeps your books accurate and your stress low.
During reconciliation, look for three things. First, confirm every transaction is categorized correctly. Second, confirm no transactions are missing. Third, confirm no duplicate transactions exist. If the ending balance matches your bank statement, your books are clean for that month.
Step Seven: Establish Clear Financial Boundaries
The technical cleanup is only half the battle. The other half is changing the habits that created the mess in the first place. Without new habits, the separation you build today will erode within months.
- Never carry personal purchases on a business card
- Never pay business expenses from a personal account
- Pay yourself a consistent owner draw on a schedule
- Review your books weekly to catch errors early
- Keep a separate wallet or card holder for business
- Train any staff on the separation policy immediately
Common Mistakes During the Separation Process
Even with a clear plan, business owners make predictable mistakes during the cleanup. Knowing these pitfalls in advance saves you time and money.
Deleting Transactions Instead of Reclassifying
When you find a personal expense in your business account, never delete the transaction. Deleting removes the record entirely and creates a gap in your reconciliation. Instead, reclassify the transaction to an owner draw account. The transaction stays in your books, but it no longer distorts your business expense categories.
Guessing on Old Transactions
When you cannot remember what a transaction from two years ago was for, do not guess. A guess creates a false record that can fail under audit. Instead, search for supporting documentation. Check your email for receipts, look at the merchant website, or contact the vendor. If you truly cannot substantiate a transaction, it is safer to classify it as an owner draw than to claim it as a business deduction you cannot prove.
Trying to Clean Up Everything at Once
The volume of commingled transactions can be paralyzing. Trying to clean up multiple years in a single weekend leads to burnout and errors. Break the work into monthly chunks. Complete one month fully before moving to the next. This approach maintains quality and keeps momentum sustainable.
The Zion Approach and Strategy
We have guided countless business owners through the separation process, and we have refined our methodology to make it as painless as possible. Our approach is built on a single principle: we never fabricate a number. Every reclassification we make is backed by documentation or a defensible logical basis.
We start by mapping your current financial landscape. We review every account you have used for business or personal purposes and identify the full scope of the commingling. This mapping gives us a clear picture of the work ahead and prevents surprises later in the process.
Next, we open your new dedicated business accounts and connect them to QuickBooks Online. We configure your chart of accounts with clean, logical categories tailored to your specific industry. We set up bank feeds so your new transactions flow automatically into your books without manual entry.
For the historical cleanup, we work month by month. We export your old statements, sort every transaction, and reclassify each one with supporting documentation. We flag any transaction that lacks clear documentation and work with you to reconstruct the details. We never rush this step because accuracy here protects you for years.
We also implement a weekly review cadence instead of a monthly one during the first ninety days after separation. This frequent review catches any old habits that creep back in and reinforces the new boundaries. Once the new habits are solid, we transition to a standard monthly reconciliation schedule.
Finally, we document the entire separation process. We create a clear record of every reclassification, every owner draw, and every owner contribution. This documentation becomes your audit defense file. If the IRS ever questions your historical records, you have a complete, professional paper trail that demonstrates your commitment to fiscal integrity.
You Can Do This Alone, But You Do Not Have To
The steps in this guide are actionable and clear. You can open a business account, rebuild your chart of accounts, and reclassify your historical transactions on your own. Many business owners do exactly that. But the process takes time, requires precision, and carries real risk if done incorrectly.
An unshakeable financial foundation requires more than good intentions. It requires a dedicated partner who knows your business, understands the tax implications of every reclassification, and stands behind the accuracy of your books. When your foundation is solid, your business can grow without the weight of financial uncertainty holding it back.
We do not just clean up your books. We build the systems and habits that keep them clean permanently. When our clients grow, we grow too. That is the foundation of a real partnership.
Related Insights
View all insights
What to Do When You Have Mixed Personal and Business Expenses for Months
Many business owners fall into the trap of paying for business expenses with a personal credit card. They assume they will sort it out later when they have more time.
How to Reconstruct Missing Business Transactions When You Have No Records
Missing business transactions create a specific kind of fear. A structured reconstruction process rebuilds your financial history from secondary sources.
My Books Are a Complete Mess: Where to Even Start Cleaning Up
Many business owners open their accounting software, see hundreds of uncategorized transactions, and immediately close it. The mess feels so enormous that paralysis sets in.